Accounting for Non-Cash Contributions
Contributions can be made to a nonprofit in either cash or property. Non-cash contributions can be tangible or intangible. Tangible property could be vehicle donations,
Contributions can be made to a nonprofit in either cash or property. Non-cash contributions can be tangible or intangible. Tangible property could be vehicle donations,
Volunteers are an integral part of many nonprofit organizations. Some organizations depend on their very survival by incorporating volunteers. Since volunteers are non-paid staff, does
All nonprofit organizations that expend $750,000 and more are required to have a single audit under the Uniform Guidance One of the required statements included
A subrecipient is an organization that receives federal awards from a pass-through entity rather than directly from the federal grantor to carry out a program.

Accounting for grant revenue is vital for the nonprofit organization. Careful attention to detail must be provided throughout the life of the grant. In addition
All nonprofit organizations, even the smallest of nonprofits, benefit from having a well-defined year end closing process. The first step is to determine the procedures
Smaller nonprofit organizations often do not have the volume of transactions to require multiple level controls. Too many controls can unnecessarily slow the accounting process.

Part of a nonprofit organization’s board of director’s and management’s fiscal responsibility is a review of the information return, form 990. The review ensures the

The operating reserve is cash to be used in the organization. It is part of an overall cash flow plan. Reserves can be for a
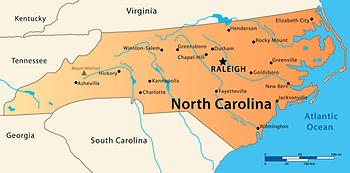
Recently, I overheard a board member of a North Carolina nonprofit state they did not have to charge sales tax because they are exempt. Nonprofit